No deposit equipment finance lets you fund the machinery or equipment your business needs without using cash upfront.
Most equipment finance structures ask for a deposit between 10% and 30%, but no deposit options exist when the lender is confident the asset holds its value and your business can service the repayments. This approach keeps your working capital intact while the equipment starts earning for you immediately.
Which Equipment Qualifies for No Deposit Finance
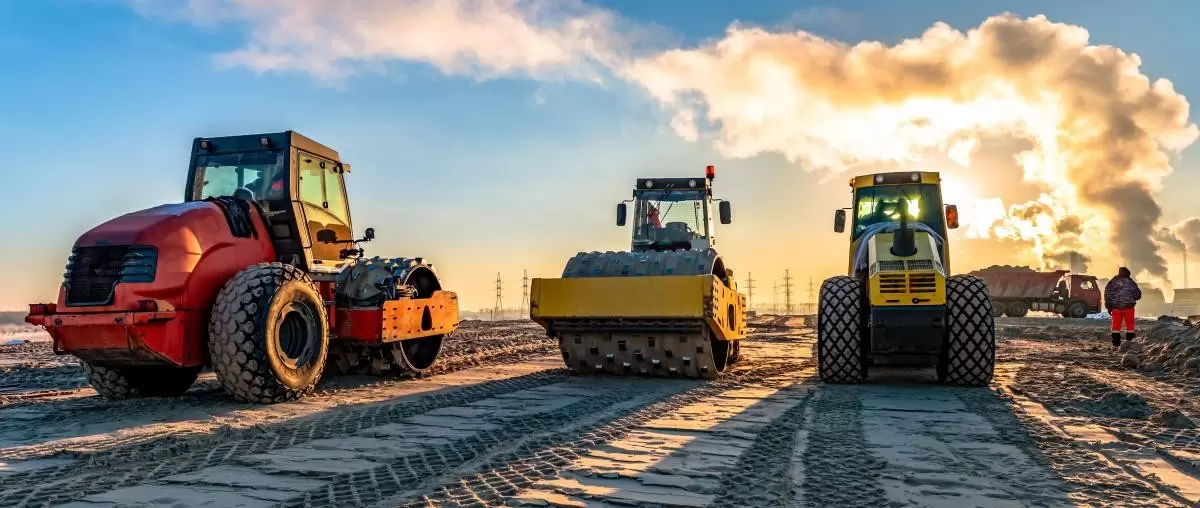
Lenders focus on resale value and demand when deciding whether to finance equipment without a deposit. Excavators, forklifts, trucks, tractors, cranes, and medical imaging equipment typically qualify because they hold their value and have active second-hand markets. Manufacturing machinery, restaurant kitchen equipment, and specialised tools often need a deposit because they're harder to resell if the loan defaults.
Consider a civil contractor looking to add a 20-tonne excavator to their fleet. The machine has strong resale demand across construction and landscaping, so the lender offers full finance based on an invoice and a two-year trading history showing consistent revenue. The contractor keeps $60,000 in the bank account instead of tying it up as a deposit, using that buffer for fuel, wages, and unexpected repairs during the first quarter.
How Lenders Assess Your Application Without a Deposit
Your business financials carry more weight when there's no deposit involved. Lenders want to see at least 12 months of trading history, steady revenue, and a clean payment record with suppliers and existing finance. They'll also check your tax lodgements and BAS statements to confirm the business generates enough income to cover the new repayment without stretching cashflow.
A rural medical practice wanting to finance an ultrasound machine might have limited assets but two years of Medicare billing records and no late payments on existing leases. That track record gives the lender confidence to approve the finance without requiring upfront cash, even though the equipment itself is highly specialised.
Ready to get started?
Book a chat with a Finance Broker at Red Fox Asset Finance today.
Chattel Mortgage vs Lease for No Deposit Deals
Both structures can work without a deposit, but they suit different tax positions. A chattel mortgage lets you claim depreciation and interest as deductions, and you own the asset from day one. A lease keeps the equipment off your balance sheet and bundles the entire repayment as an expense, which works for businesses that want to preserve borrowing capacity or don't need to show the asset as equity.
The civil contractor mentioned earlier chose a chattel mortgage because they wanted to claim the instant asset write-off and own the excavator outright once the term finished. If they'd been a larger business already carrying significant debt, a lease would have kept the liability off their books and freed up capacity for other funding.
Red Fox Asset Finance can help you compare both structures based on your current tax position and what you're planning over the next few years. If you're considering plant and machinery finance or equipment finance more broadly, we'll walk through which option fits your situation.
What Happens When the Asset Is Your Only Security
No deposit finance usually means the equipment itself is the only security, so the lender takes a registered interest over the asset. If your business is newer or cashflow is tight, they might also ask for a director's guarantee or a second security like a property or vehicle you already own. That's not common with high-value, high-demand equipment, but it can come up with lower-value items or industries the lender sees as higher risk.
A transport operator financing three forklifts for a new warehouse might be asked for a guarantee if the business has been trading for less than two years, even though the forklifts themselves are in demand. The guarantee doesn't change the repayment or the structure, but it does mean the director is personally liable if the business can't meet the payments.
Approval Timeframes and What You'll Need
Most no deposit applications take between 24 and 48 hours to assess once the lender has your financials. You'll need recent tax returns, BAS statements, a driver's licence, and a quote or invoice for the equipment. If the asset is used, the lender may also want an independent valuation or an inspection report to confirm its condition.
Speed matters when you've found the right machine at the right price, so having your documents ready before you start shopping cuts down the time between approval and delivery. We regularly see approvals come through within a day when the business has clean financials and the equipment is straightforward to value.
Structuring Repayments Around Seasonal or Project-Based Income
Some lenders offer flexible repayment structures that match your income cycle. A quarterly repayment schedule suits agriculture contractors who invoice heavily after harvest, while monthly payments work for businesses with steady cashflow year-round. Structuring the term to align with how you actually earn keeps the repayment manageable without forcing you to hold excess cash just to meet a fixed schedule.
If your business income varies or you work on long project cycles, mention that when you apply. The lender can adjust the structure before settlement rather than locking you into monthly payments that don't suit how you operate. You can explore farm equipment finance or tractor loans if you're in agriculture and need that kind of flexibility.
How This Fits With Other Business Funding
No deposit equipment finance doesn't usually affect your ability to access other funding, but it does add a liability to your business, so future lenders will include the repayment when they assess your serviceability. If you're planning to apply for a business loan or expand your overdraft in the next 12 months, factor in the equipment repayment when you're working out how much you can afford.
The medical practice that financed the ultrasound machine kept their repayment under $1,500 a month specifically because they wanted to apply for a fit-out loan six months later. That decision gave them room to take on both commitments without overextending their cashflow.
Call one of our team or book an appointment at a time that works for you. We'll walk through what you're looking to fund, how your business is tracking, and whether no deposit finance makes sense for what you're planning next.
Frequently Asked Questions
What types of equipment can I finance without a deposit?
Equipment with strong resale value like excavators, forklifts, trucks, tractors, cranes, and medical imaging equipment typically qualifies for no deposit finance. Lenders focus on assets with active second-hand markets that hold their value if they need to recover the loan.
Do I need to provide a personal guarantee for no deposit equipment finance?
Personal guarantees are not always required but may be requested if your business has been trading for less than two years or if the equipment has lower resale value. High-value, high-demand assets usually don't need additional security beyond the equipment itself.
How long does approval take for no deposit equipment finance?
Most applications are assessed within 24 to 48 hours once the lender receives your financials. You'll need recent tax returns, BAS statements, a driver's licence, and a quote or invoice for the equipment to speed up the process.
Can I structure repayments around seasonal income?
Yes, some lenders offer quarterly or custom repayment schedules that align with seasonal or project-based income. This approach works particularly well for agriculture contractors or businesses with uneven cashflow throughout the year.
Will no deposit equipment finance affect my ability to get other business funding?
No deposit equipment finance adds a liability to your business, so future lenders will include the repayment when assessing your serviceability. It doesn't prevent you from accessing other funding, but you should factor in the repayment when planning additional borrowing.